
ISLAMABAD, Oct 8 (ABC): Developing economies are placing greater emphasis on longer debt maturities, diversified funding sources and concessional financing as higher global government bond yields increase the cost of refinancing external debt.
The renewed focus on debt management comes as several developing economies regain access to international capital markets following an exceptionally difficult debt cycle. However, elevated benchmark yields continue to make new borrowing and refinancing expensive, particularly for weaker-rated sovereigns.
Sarwat Shah, Business Development Executive at JS Investments, told Wealth Pakistan that the concern for developing economies was not simply rising US yields. Rather, it was the higher benchmark against which lenders calculate their borrowing costs.
“When the risk-free rate rises sharply, emerging market borrowers start from a much more expensive base even if their individual credit spreads do not deteriorate. For countries approaching sizeable debt maturities, that can turn refinancing into a much more difficult and costly exercise,” she said.
Shah said countries with weaker external buffers needed to carefully weigh their financing options. These included paying higher yields to retain market access, delaying debt issuance where possible or relying more heavily on multilateral and bilateral financing.
Rising US Treasury yields increase borrowing costs
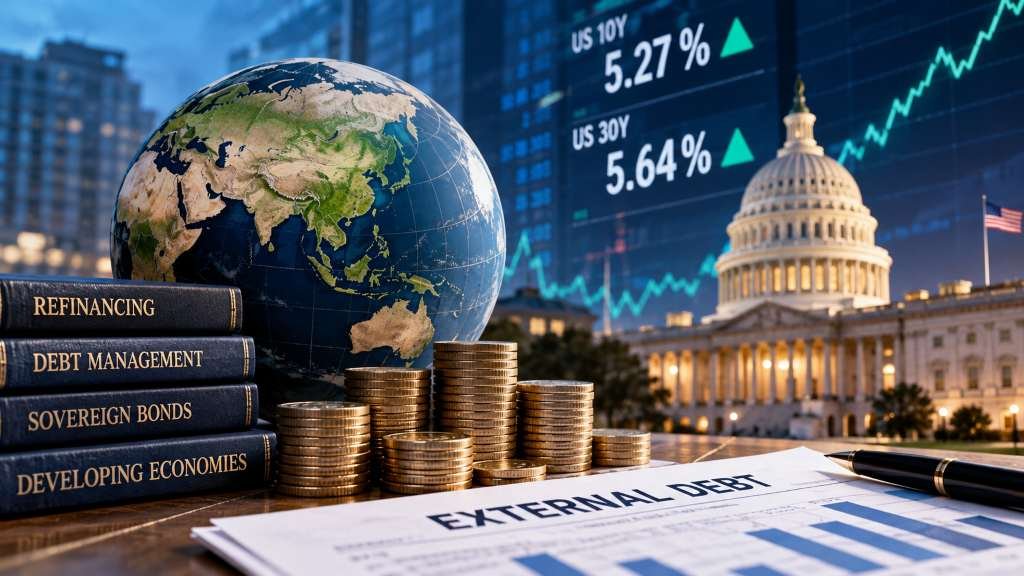
US Treasury data show that the 10-year Treasury yield reached 5.27% on October 6, while the 30-year yield stood at 5.64%. On September 16, the same maturities stood at around 4.23% and 4.43%, respectively. The increase illustrates how quickly long-term global borrowing benchmarks have changed.
However, the impact on developing-country borrowing conditions has not been uniform.
A recent World Bank analysis found that dollar-denominated sovereign borrowing costs for emerging market and developing economies rose less than US Treasury yields. Narrowing sovereign spreads helped absorb part of the increase, although absolute financing costs remained high.
Median yields for weaker-credit developing economies stand at around 9%, compared with 6.3% for stronger-credit borrowers. Countries carrying a larger share of short-term debt face median yields of about 7%, against 6.1% for those with lower short-term exposure.
Maham Imran, Research Associate at Foundation Securities, said refinancing stress tended to emerge when high borrowing costs coincided with concentrated repayment schedules.
“A country may have manageable debt on paper, but if a large portion matures while international yields are elevated, the refinancing rate can be far higher than the rate on the debt being replaced. That raises future interest payments and can progressively consume fiscal space,” she told Wealth Pakistan.
“For vulnerable economies, the pressure can then spread beyond the debt account. Higher external financing costs can weigh on foreign exchange reserves, currencies, domestic interest rates and ultimately the government’s ability to allocate resources towards development spending,” she added.
Developing economies face heavy external debt burden
The renewed emphasis on refinancing strategies follows an exceptionally difficult debt cycle for developing economies. According to World Bank estimates, low- and middle-income countries paid a record $415.4 billion in interest on external debt in 2024. This was more than twice the level recorded a decade earlier.
Between 2022 and 2024, developing economies paid $741 billion more in principal and interest than they received through new external financing. This represented the largest net debt outflow in at least five decades.
Nevertheless, bond markets have begun reopening. In 2024, private bond investors provided developing economies with around $80 billion more in fresh financing than they collected in repayments and interest. However, borrowing rates remained close to 10%, roughly twice their pre-2020 levels.
The World Bank has projected total external debt service by low- and middle-income economies to decline from an estimated $1.2 trillion in 2025 to $918 billion by 2027. The projection partly assumes easing global financing conditions.
However, higher global yields make careful management of debt maturities and funding sources increasingly important. Such measures could help developing economies manage their repayment obligations without adding excessive pressure to public finances.
Pakistan focuses on concessional financing, longer maturities
Pakistan is partially insulated from immediate global bond-market repricing because of the composition of its external public debt.
According to the Finance Ministry, around 75% of the country’s approximately $92 billion external public debt consists of concessional and long-term multilateral and bilateral financing.
The government has also made longer maturities, concessional borrowing and diversification of funding sources central to its debt-management strategy. These measures aim to reduce dependence on any single financing channel during periods of global market volatility.
Imran said the latest developments reinforced the importance of managing refinancing risks well before repayment obligations became immediate.
“The lesson for developing economies is that market access alone is not enough. The maturity structure and the price at which debt is refinanced matter just as much. A prolonged period of high global yields can turn what appears to be a liquidity problem into a much broader fiscal constraint,” she said.